Credit Rating vs Credit Score | Know the Key Differences | AEBITDA
When businesses seek funding or individuals apply for loans, lenders need a reliable way to assess financial risk. Two commonly used measures are credit ratings and credit scores. While people often confuse these terms, they serve different purposes and apply to different types of borrowers.
Understanding the difference between a credit rating and a credit score is important for anyone involved in financial planning, borrowing, or investment decisions. Although both evaluate creditworthiness, the methods, users, and outcomes vary significantly.
Understanding Credit Rating and Credit Score
At a basic level, both a credit rating and a credit score help lenders determine the likelihood that a borrower will repay their obligations. However, the type of borrower being assessed is different.
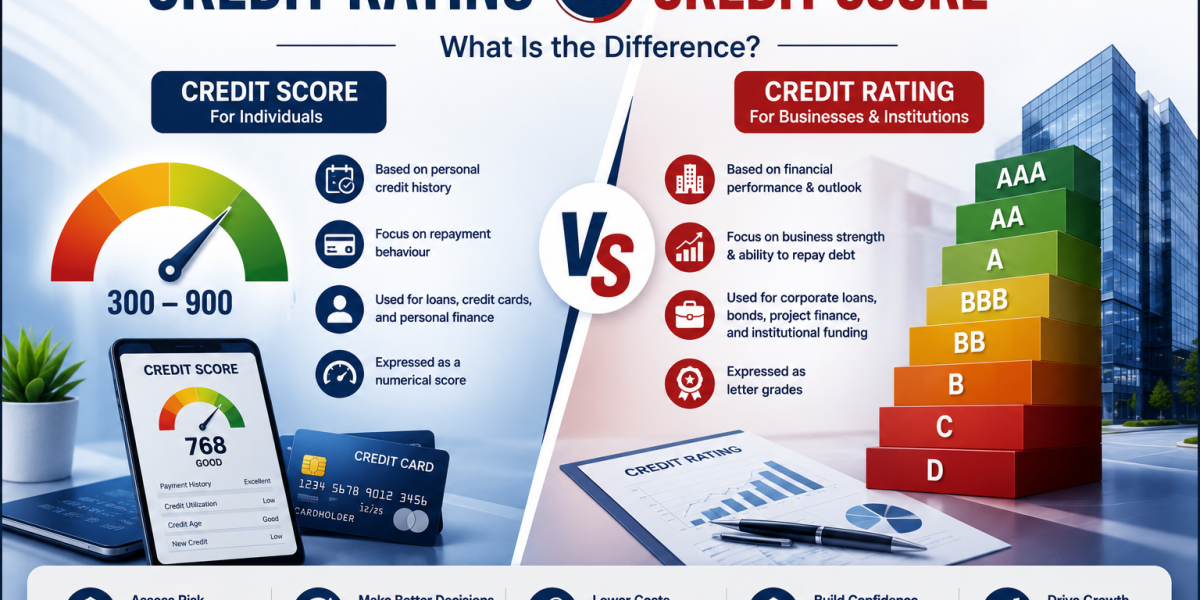
A credit score is designed for individuals. It reflects a person’s borrowing behaviour and repayment history.
A credit rating is primarily assigned to businesses, corporations, government entities, and financial instruments. It represents an independent assessment of an organisation’s financial strength and its ability to meet debt obligations.
This distinction forms the foundation of the difference between a credit rating and a credit score.
What Is a Credit Score?
A credit score is a numerical indicator of an individual’s creditworthiness. Financial institutions use this score to evaluate the risk associated with lending money to a person.
Credit scores are typically calculated using factors such as the following:
- Loan repayment history
- Credit card payment behaviour
- Credit utilisation ratio
- Existing debts
- Length of credit history
- Number of recent credit applications
A higher credit score generally indicates stronger repayment discipline and lower lending risk.
When an individual applies for a personal loan, home loan, vehicle loan, or credit card, lenders often review the credit score before making a decision.
What Is a Credit Rating?
A credit rating is a professional assessment of a company’s or institution’s ability to repay debt and honour its financial commitments.
Credit rating agencies evaluate a wide range of factors before assigning a rating, including:
- Financial performance
- Profitability
- Cash flow stability
- Debt servicing capability
- Industry outlook
- Business risks
- Management quality
Unlike a credit score, which data-driven models primarily generate, a credit rating often requires detailed financial analysis and expert review.
Credit ratings frequently evaluate businesses seeking corporate loans, project finance, working capital facilities, or institutional funding.
Credit Rating vs Credit Score: Key Differences
1. Type of Borrower Evaluated
The most obvious difference is the subject being assessed.
Credit Score:
Used for individuals.
Credit Rating:
Used for businesses, corporations, government entities, and debt instruments.
2. Method of Assessment
The evaluation process differs significantly.
Credit Score:
Generated using automated models based on an individual’s credit history and repayment behaviour.
Credit Rating:
Assigned after analysing financial statements, business performance, industry conditions, management quality, and future outlook.
3. Format of Expression
The way these assessments are presented is also different.
Credit Score:
Expressed as a numerical value.
Credit Rating:
Expressed using letter grades such as AAA, AA, A, BBB, BB, and lower categories.
4. Purpose
Both measures help assess risk but serve different financial needs.
Credit Score:
Supports personal lending decisions such as home loans, personal loans, and credit cards.
Credit Rating:
Supports corporate lending, bond issuance, project financing, and institutional investment decisions.
5. Complexity of Analysis
A credit score is based primarily on historical credit behaviour.
A credit rating examines both historical performance and future business prospects. It includes qualitative and quantitative assessments, making it a more comprehensive evaluation.
Why Credit Scores Matter
For individuals, a strong credit score can provide several benefits:
- Faster loan approvals
- Better interest rates
- Higher credit limits
- Easier access to financial products
A poor credit score may result in loan rejections or higher borrowing costs.
Maintaining repayment discipline and responsible credit usage can help improve credit scores over time.
Why Credit Ratings Matter
For businesses, credit ratings play a critical role in accessing capital and building credibility.
A strong credit rating can help organisations:
- Secure larger funding facilities
- Negotiate better lending terms
- Attract investors
- Build confidence among financial institutions
- Strengthen market reputation
Many lenders use credit ratings as a key component of their risk assessment process.
Can both improve?
Yes. Both credit scores and credit ratings can improve with consistent financial discipline.
Individuals can strengthen their credit scores by:
- Paying bills on time
- Managing credit utilisation carefully
- Avoiding excessive borrowing
- Monitoring credit reports regularly
Businesses can improve their credit ratings by:
- Enhancing profitability
- Maintaining strong cash flows
- Reducing excessive debt
- Improving financial reporting
- Strengthening operational performance
While improvements may take time, disciplined financial management often produces positive results.
How AEBITDA Supports Businesses
Businesses often face challenges in understanding what influences their credit profile. AEBITDA helps organisations navigate this process with structured advisory services.
By analysing financial performance, identifying gaps, and aligning business practices with lender expectations, AEBITDA helps companies strengthen their financial credibility and improve their funding readiness.
A strong credit rating is not simply a financial metric; it is a strategic asset that can influence long-term growth opportunities.
Frequently Asked Questions
What is the main difference between a credit rating and a credit score?
A credit score measures an individual's creditworthiness, while a credit rating evaluates the financial strength of a business, corporation, or government entity.
Who receives a credit score?
Credit scores are assigned to individuals based on their borrowing and repayment history.
How is a credit score calculated?
It is based on factors such as repayment history, credit utilisation, credit mix, and the length of credit history.
Final Thoughts

Although people often use the terms interchangeably, credit ratings and credit scores serve very different purposes. A credit score measures an individual’s borrowing behaviour, while a credit rating assesses the financial strength and repayment capacity of a business or institution.
Understanding the difference between the two helps borrowers make informed decisions and prepare more effectively for funding opportunities. Whether you are an individual seeking personal finance or a business pursuing institutional funding, maintaining a strong credit profile remains essential for long-term financial success.
With expert guidance from AEBITDA, businesses can strengthen their financial position, improve credibility, and enhance access to growth capital.
Image Reference: Magnific
Disclaimer: All trademarks, logos, and brand names are the property of their respective owners. All company, product, and service names used on this website are for identification purposes only. Use of these names, trademarks, and brands does not imply endorsement.